







 Covivio Hotels Revenue Grows 4.7% as European Markets Split
 Lithuanian Apartment Prices Accelerate Across Major Cities
 Georgia's Tourism Revenue Hits Record High
 Norway's Sovereign Fund Commits €1.5bn to European Warehouses
 Market Rout of October 2026: Can Branded Hotels Protect Capital?
 Residential Property Prices in Tbilisi Rise by 5.9% Year-on-Year
Dutch VAT Rates Updated
The Dutch Tax Administration has confirmed that the reduced 9% VAT rate for culture, sports and media will remain in place as of 1 January 2026. This decision formally repeals earlier plans to increase VAT on these supplies to the standard 21% rate, which had been proposed as part of the 2025 Tax Plan.
Under the initial proposal, the higher VAT rate would have applied to books, e-books, newspapers and magazines, as well as concerts, theatre and dance performances, gym memberships and access to public museums. While certain leisure activities were initially excluded, the Dutch Parliament ultimately rejected the proposal in its entirety.
Alternative measures to close the budget gap
Following the rejection of the VAT increase on culture and sports, the government identified alternative ways to compensate for the resulting budget gap. Rather than increasing taxes on cultural consumption, policymakers shifted their focus to other sectors considered more suitable for higher indirect taxation.
As a result, cultural institutions, publishers and sports organisations retain access to the reduced VAT rate, helping to preserve affordability and demand across these sectors.
Hotel Accommodation VAT Increased to 21% in January 2026
From 1 January 2026, the Netherlands applies 21% VAT to most short-stay accommodation, replacing the previous 9% rate. The rule covers hotels, boarding houses and other qualifying short stays. The Dutch Tax Administration confirms that the 21% rate also applies to accommodation provided in 2026 where the guest paid in advance during 2025. The change is already in force and should no longer be described as a proposal awaiting legislative approval.
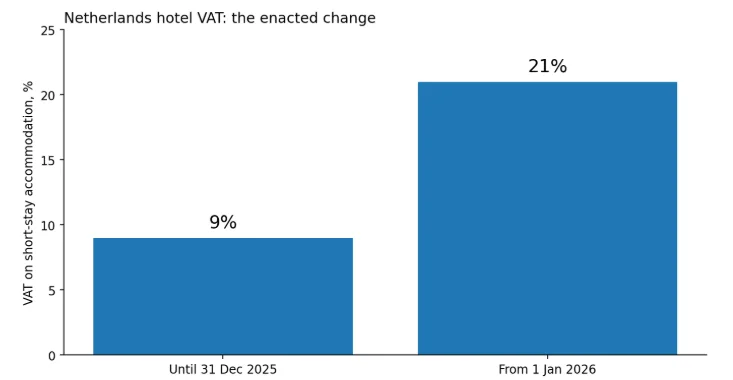
Chart: enacted Dutch VAT rate on short-stay accommodation, 2025 versus 2026. Source: Belastingdienst; International Investment.
The 12-percentage-point increase in VAT does not imply that all room prices or hotel profits changed by 12%. Its commercial effect depends on pricing and the extent to which an operator can pass the additional tax on to guests. The new rate is material when assessing hotel revenues, operating costs and investment returns.
VAT changes for agricultural goods
Separate VAT changes are already scheduled to take effect from 1 January 2025, affecting specific agricultural goods in the Netherlands. For a range of non-food agricultural and horticultural products, the VAT rate will increase from 9% to 21%.
These measures coincide with the introduction of the EU small business scheme, including its extension to foreign companies, and require businesses in the agricultural sector to reassess pricing strategies and VAT compliance.
As reported by International Investment experts, the Dutch government’s decision to retain the reduced VAT rate for culture and sports underscores the political and social importance of these sectors. At the same time, the shift toward higher VAT on accommodation and certain agricultural goods highlights a pragmatic approach to revenue generation. Businesses exposed to tourism and agriculture should factor these changes into medium-term planning, while cultural and media organisations benefit from greater regulatory stability.