







 Lithuanian Apartment Prices Accelerate Across Major Cities
 Georgia's Tourism Revenue Hits Record High
 Norway's Sovereign Fund Commits €1.5bn to European Warehouses
 Residential Property Prices in Tbilisi Rise by 5.9% Year-on-Year
 Ras Al Khaimah Hotels Reposition Ahead of Wynn Opening
 The 10 Hungriest Countries in the World
Market Rout of October 2026: Can Branded Hotels Protect Capital?
International Investment | Analysis | October 31, 2026 | English edition
On October 30, 2026, US technology stocks fell sharply, crypto markets faced a wave of selling after a major Binance security breach, and even gold and silver declined. For property investors, the question is practical: which assets can service debt and sustain cash flow if demand weakens? Branded luxury hotels offer a different income model from listed technology companies and individually rented resort apartments. Their performance still depends on occupancy, room rates, operating costs and the purchase price.
The Nasdaq Composite fell 2.9% on October 30, while the S&P 500 lost 1.8%. December gold and silver futures declined 3.29% and 5.93%, respectively. Following the Binance incident, roughly $1.5 billion–$1.6 billion in leveraged crypto positions were liquidated over 24 hours. These figures represent different instruments and market measures; combining them into a single global loss would be misleading. The equity closes were reported by Associated Press, metal futures by The Wall Street Journal and crypto liquidations by CoinDesk citing CoinGlass.
Several shocks converged
The correction in Chinese AI shares did not begin on Halloween. Reuters reported that the STAR50 technology and semiconductor index had fallen around 40%, wiping out roughly $480 billion in market value over less than four months. Separate market reporting put MiniMax and Zhipu more than 80% below earlier highs by October 22; those company-specific estimates need another closing-price check. Neither figure is a one-day decline.
In the US, investors are questioning how quickly billions spent on computing capacity will translate into profit. Reuters estimated that Nasdaq 100 companies faced a possible loss of more than $2 trillion in market value across October. This is a monthly estimate for one index, not a global figure for October 30. Market losses in China and America also cannot simply be summed without checking constituent overlaps and measurement periods.
Binance disclosed an estimated $6.3 billion in unauthorized outflows linked to an October 29 security breach. The exchange said approximately $3 billion had been frozen and pledged to cover user losses while investigators worked to determine the cause. Bitcoin briefly approached $76,400 and Ether fell below $2,200. Forced liquidation of leveraged positions amplified the decline. The hack was a distinct crypto-market shock; evidence does not establish it as the cause of simultaneous equity and metal selling.
Eric Jardine, head of research at Chainalysis, told Reuters on October 30: “The investigation is ongoing, and we cannot yet confirm the cause of the hack.” The firm's investigators were tracking stolen assets across multiple blockchains.
Gold and silver were no exception to the selling pressure. Reuters reported intraday spot declines of approximately 3.5% and 6.5% by 2:13 p.m. New York time on Friday. The widely circulated figures of 4.4% for gold and 9.1% for silver refer to a two-day move from Wednesday's close to Friday morning, not a single session. The December futures settled down 3.29% and 5.93% on October 30. Higher interest-rate expectations and liquidity needs can produce a sharp selloff even in assets usually considered defensive.
Peter Grant, vice-president and senior metals strategist at Zaner Metals, told Reuters: “Ongoing concerns about inflation have multiple central banks continuing to tilt hawkish.” The prospect of persistently high interest rates weighs on metals that do not generate interest income.
A black swan—or a reminder of correlated risk?
A 'Black Friday on Halloween' accurately conveys the market mood. Calling the whole episode a proven black swan is less convincing: expensive AI valuations had been debated for months, while the Binance breach was difficult to predict. Together, the events showed that liquidity stress can make unrelated assets fall at once. Investors should distinguish a sudden shock from a foreseeable repricing and avoid assuming that a hedge must rise every day shares decline.
Hotels have suffered steep losses in previous crises. STR data show a 17%–22.3% fall in US midscale, upscale and luxury RevPAR over 2008–2009, while luxury gross operating profit per available room fell 36.1%. US hotel RevPAR dropped 47.5% in 2020. International branding may strengthen distribution, but it does not remove payroll, maintenance or exposure to a decline in travel.
Hotel transactions stalled in late 2008 and 2009 before activity gradually returned in 2010, according to HVS. Buyers with cash could negotiate once indebted owners needed liquidity. The lesson is not that hotel prices rise automatically after a market crash. Debt maturity, operating income and the entry valuation determine whether an investor benefits from buying during a downturn.
Which parts of real estate are most exposed?
Buildings are not repriced every minute. Their losses may only become visible when owners seek refinancing, a new appraisal or a buyer. Open-ended property funds face a particular mismatch: investors can request redemptions more quickly than managers can sell large assets at a fair price.
European offices are facing a liquidity test. Financial Times reporting on MSCI data puts Q3 2026 office transactions at €8.8 billion, down 33% year on year and the weakest quarterly value since 2009. Savills estimated withdrawals of €17.3 billion from German open-ended property funds since early 2024. Quarterly deal value and multi-year fund redemptions are different measures and cannot be added. Both indicate how debt costs and redemption demands can force property repricing.
Secondary offices requiring expensive refurbishment, highly leveraged developments and oversupplied holiday apartments can be particularly vulnerable when borrowing becomes costly. A heavily indebted five-star hotel may still be less defensive than a fully let rental property. The relevant comparison is cash flow after costs, debt maturities, liquidity and realistic resale pricing—not the asset label alone.
|
Property sector |
Key exposure |
What to check |
|
Secondary offices |
Refinancing, renovation costs |
Debt, vacancy |
|
Holiday apartments |
Oversupply, seasonal demand |
Net income, ADR |
|
Branded luxury hotels |
Operating costs, travel demand |
RevPAR, GOP, operator |
|
Rental housing |
Debt rates, arrears |
Rent roll, LTV, maturity |
Why branded luxury hospitality attracts patient capital
International hotel brands bring reservation networks, loyalty members, corporate distribution and professional revenue management. Full-service resorts can generate additional income from dining, wellness and events; they also carry fixed operating costs that do not disappear in a weak season. Investors need evidence that the operator can convert brand visibility into reliable net cash flow.
Cushman & Wakefield reported more than €11.5 billion in European hotel transactions in the first half of 2026, with luxury and upper-upscale properties accounting for 46% of transaction value. European RevPAR increased 3% year on year. In a separate investor survey, 86% of respondents planned to maintain or increase their hotel allocations in 2026. This sentiment predates October's selloff; it does not prove that money from AI stocks, gold or crypto has already moved into hospitality.
Frederic Le Fichoux, head of Hotel Transactions EMEA at Cushman & Wakefield, described the first half of 2026 as “a highly selective market and not a market that is weakening.” He pointed to strong demand for premium properties in established locations.
The mechanism can work in specific markets. CBRE's September 2026 research on Australia and New Zealand found that luxury hotel demand grew faster than the broader accommodation sector and that occupancy remained broadly stable at around 78%–79% despite new supply. That finding cannot be transplanted directly to the Georgian Black Sea coast. It illustrates the conditions that can underpin premium assets: a differentiated product, sustainable demand and room rates supported by service quality.
Georgia and Batumi: rising demand, clear seasonality
Georgia entered the autumn with rising tourism receipts. The Georgian National Tourism Administration recorded 6.11 million international traveller visits and 4.40 million overnight tourist visits in January–September 2026. Overnight visits rose 2.3% year on year, and international travel revenue grew 4.4% to roughly $3.8 billion. These numbers are visits, not unique travellers, and they do not measure occupancy or profits at any one resort in Gonio.
TBC Capital data cited by BM.ge show that Georgia's major branded hotels averaged 65% occupancy in January–September 2026, up three percentage points year on year, while ADR rose 14% to $154. September occupancy reached 86%. A model for a resort in Gonio must be based on the annual demand pattern rather than the peak month alone, with particular care for winter occupancy, air connectivity and the cost of full-service facilities.
Wyndham Grand Batumi Gonio: a 10% contract or up to 17%
European Village is developing Wyndham Grand Batumi Gonio in Gonio near Batumi, with hotel rooms and residence-style products under the Wyndham Grand brand. In July 2024 Aimbridge Hospitality EMEA announced a management agreement for Aqua, Family Club and Riviera. The participants have different roles: Wyndham provides its hotel brand and standards; European Village is the developer and contractual counterparty for purchasers; Aimbridge provides hotel management under the agreements announced.
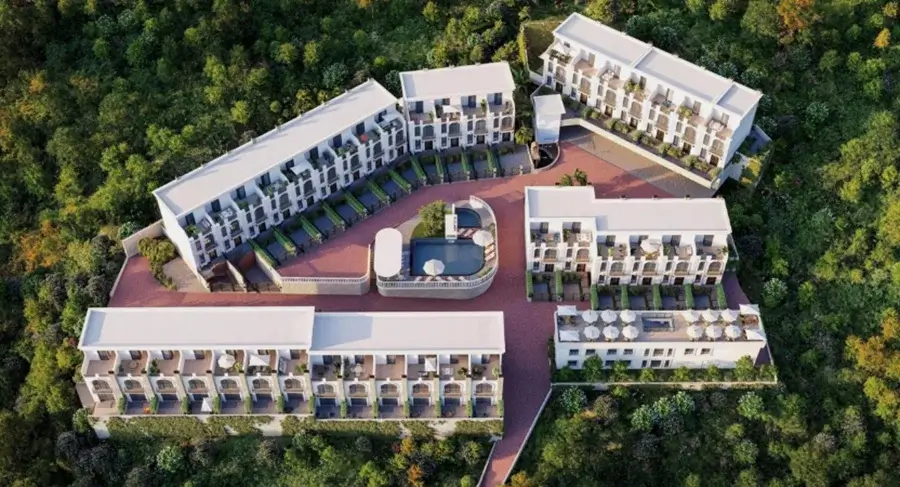
Project rendering of Wyndham Grand Batumi Gonio. Source: Esteliti. This is not a photograph of a completed, operational hotel.
European Village offers two return models. The first provides a 10% annual return guaranteed under the buyer's contract, independent of hotel occupancy. The developer states that the payment obligation applies after the property has been paid for, including during construction. The second, sometimes described as the self-managed income option, offers up to 17% annually from actual hotel operating results. Aimbridge Hospitality manages the property; income is distributed through a common pool according to the owner's share, room category and expenses. The 17% figure is a potential maximum, not a fixed payment. Buyers should compare the signed contracts, fees and distribution formula.
|
Criterion |
10% contracted return |
Up to 17% operating model |
|
Basis |
Fixed contractual payment |
Actual hotel operating income |
|
Occupancy |
Not linked to room occupancy |
Depends on ADR, costs and occupancy |
|
Evidence |
Signed agreement, payment terms |
Operator reports, pooled revenue rules |
|
Main checks |
Obligor, term and payment schedule |
Costs, payout formula and evidence |
Completion status varies by building. Some units were still marketed as under construction in 2026. Before treating a forecast as cash flow, buyers should verify the specific building's commissioning documents, intended opening date and independently comparable hotel performance.
A hotel room in a managed resort differs from a studio marketed individually on short-term rental platforms. The operator takes over distribution and guest services, while owners accept the resort's revenue-allocation rules and common costs. The premium for an international brand is justified only when the purchase price and the project's net operating performance support it.
International Investment's Georgia real-estate review cites Galt & Taggart data showing 13,866 unsold apartments in the Batumi developments surveyed at the end of H1 2026. That inventory adds competition for investors seeking to resell ordinary rental studios. A branded hotel is not automatically a better investment, but its integrated services, operator and distribution model distinguish it from an individually rented apartment.
An opportunity window, not a guaranteed refuge
A short-lived market correction may leave premium property pricing largely unchanged. A longer liquidity squeeze may produce motivated sellers, developers looking for capital and more realistic pricing. Buyers with cash and a long horizon may then be able to negotiate discounts, payment schedules and protections unavailable during speculative booms. A deep recession, however, could hit travel budgets, room rates and construction costs at the same time. Luxury assets would not escape that scenario.
The October market rout has not automatically repriced luxury property. It does demonstrate how fast liquidity can evaporate. Wyndham Grand Batumi Gonio combines an international brand, a professional operator and a 10% annual return guaranteed under the developer's agreement. An alternative model advertises up to 17% based on operating results. The investment case still rests on verified legal terms, a sensible entry price and realistic performance for the individual building.