







 Covivio Hotels Revenue Grows 4.7% as European Markets Split
 Lithuanian Apartment Prices Accelerate Across Major Cities
 Georgia's Tourism Revenue Hits Record High
 Norway's Sovereign Fund Commits €1.5bn to European Warehouses
 Market Rout of October 2026: Can Branded Hotels Protect Capital?
 Residential Property Prices in Tbilisi Rise by 5.9% Year-on-Year
Israeli Developers Start Renting Out Unsold Apartments
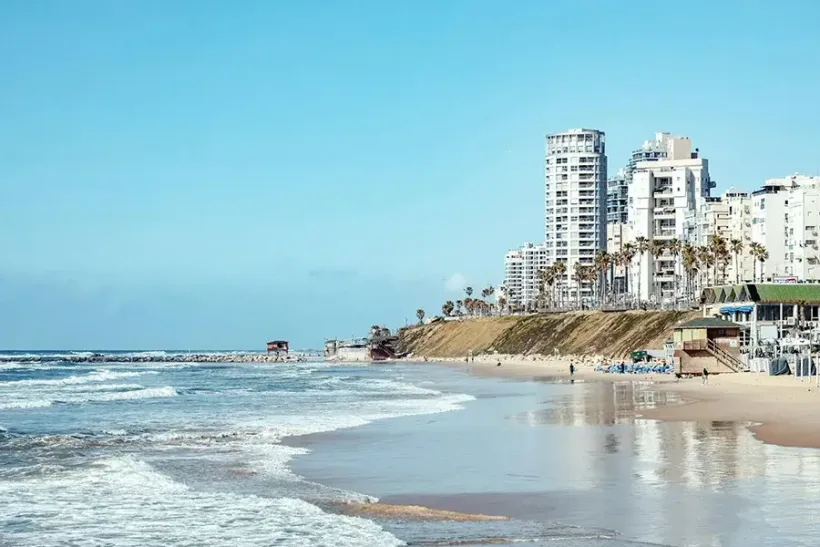
Demand for new-build homes in Israel has weakened, while the number of unsold apartments continues to grow. Developers are reluctant to cut prices and have instead begun moving some properties onto the rental market to generate income until they can be sold. This approach is already being used in projects in Modi'in and Bat Yam, Globes reports.
New-Build Apartments Enter Israel's Rental Market
Slower new-home sales and a growing inventory of unsold apartments are pushing Israeli developers to seek new solutions. Companies are offering discounts and preferential financing schemes, as well as selling properties to investment funds. Another option is to rent out homes temporarily and return them to the sales market at a later stage.
Tal Kopel, CEO of real estate platform Madlan, describes the practice as a relatively new phenomenon linked to current market conditions. With a large stock of unsold homes and steady rental demand, developers can benefit from putting completed apartments to use rather than leaving them vacant.
At the same time, companies are trying to avoid substantial price reductions. Kopel notes that large discounts can damage a project's reputation and upset buyers who previously purchased apartments at higher prices. Price cuts may also affect how the remaining units are valued by the bank financing the development.
Projects in Modi'in and Bat Yam
The new approach is already being used in several residential developments, although the terms and time frames vary. Around 20 apartments remained unsold after construction was completed at a Dona Engineering project in Modi'in. The developer has started renting them out for two years and plans to put them back on the market afterward. Tenants can sign a one- or two-year lease, with one guarantor required and a credit check conducted as part of the application process.
One Dona tenant, a father of three, told Globes that dealing with the company had proved more predictable than renting from a private landlord. The terms are set in advance, while a dedicated department handles maintenance and repairs. The developer also has an incentive to keep the properties in good condition because it intends to sell them once the rental period ends.
A different model is being used at the Panorama North project in Bat Yam's Park HaYam neighborhood. The 30-story building contains 113 apartments, around 78 of which are designated for rental for ten years. This period makes it possible to benefit from tax incentives available under Israel's Law for the Encouragement of Capital Investments. While Dona is using rentals as a temporary two-year solution, Panorama North has adopted a long-term model.
Economics of the Rental Model
Renting out completed apartments allows developers to offset some costs but does not solve the underlying issue of project financing. As long as the homes remain unsold, companies must continue servicing bank loans, while the bulk of their expected profit is delayed.
Attorney Moshe Moyal, founder of Moyal Malachi & Co, a law firm specializing in real estate and urban renewal, notes that rental payments provide an additional cash flow. At the same time, developers can reduce expenses associated with municipal taxes and the maintenance of vacant apartments.
Another advantage concerns the identification and repair of construction defects. In many cases, warranty periods for subcontractors' work begin once the property is handed over to the developer. Having tenants move in makes it possible to identify problems sooner and address them while contractors' warranty obligations are still in effect.
Under certain conditions, projects with a substantial number of rental units may also qualify for tax benefits. However, this model is not suitable for every market participant. Dror Ohev Zion, CEO of Dara Project Marketing, notes that developers with sufficient financial resources are best positioned to postpone sales.
Another option is to sell large portfolios of apartments to investment funds and companies specializing in rental housing. This allows developers to raise funds more quickly and close out project financing, although buyers acquiring large numbers of units typically demand substantial discounts.
New-Home Sales in Israel
Around 7,600 housing transactions were recorded in Israel's residential market in July, down 13.7% from June. New-home sales fell by about 20% to 2,930 units. Excluding government programs, developers sold around 1,820 properties, a monthly decline of 26%. These figures indicate that commercial demand remains considerably weaker than the headline numbers for the primary market suggest.
The May–July figures present a more positive picture. Around 25,160 homes were purchased nationwide during the three-month period, 20.8% more than in February–April and 14.6% above the same period in 2025. The primary market accounted for around 10,470 transactions, with government-subsidized programs responsible for 33.7% of them. A significant share of demand for new housing therefore continues to depend on state support.
Supply also remains high. At the end of July, 84,990 new apartments were still available for sale, equivalent to 26.9 months of supply at the current sales rate. The figure has changed little since the beginning of 2026 despite intermittent increases in demand. Official statistics include properties at different stages of construction, while completed apartments are removed from the inventory figure if they remain unsold for more than 15 months.
Market Outlook and Risks for Investors
International Investment analysts note that the emerging practice could alter the way Israel's real estate market adjusts to excess supply. Moving some unsold homes into the rental sector allows developers to maintain asking prices for longer, meaning an oversupply does not necessarily translate quickly into lower prices. Under these conditions, time on the market, financing terms and the dynamics of commercial transactions become increasingly important indicators of the sector's actual condition.
For investors, this makes individual projects and locations more difficult to assess. Stable prices alone do not indicate resilient demand when a significant share of properties remains unsold for extended periods or is shifted to a different use. Developers' debt burdens, sales volumes excluding subsidized programs and the size of the rental inventory that could eventually return to the sales market all become important factors.
Over time, apartments that are temporarily rented out could create additional supply on the secondary market. If several large projects begin selling such properties at the same time, competition could intensify. When assessing potential returns, investors should therefore consider not only current rental rates and acquisition costs, but also the amount of supply that could emerge in a particular location by the time they plan to exit the investment.