







 Covivio Hotels Revenue Grows 4.7% as European Markets Split
 Lithuanian Apartment Prices Accelerate Across Major Cities
 Georgia's Tourism Revenue Hits Record High
 Norway's Sovereign Fund Commits €1.5bn to European Warehouses
 Market Rout of October 2026: Can Branded Hotels Protect Capital?
 Residential Property Prices in Tbilisi Rise by 5.9% Year-on-Year
Investors Are Redrawing Europe’s Property Map
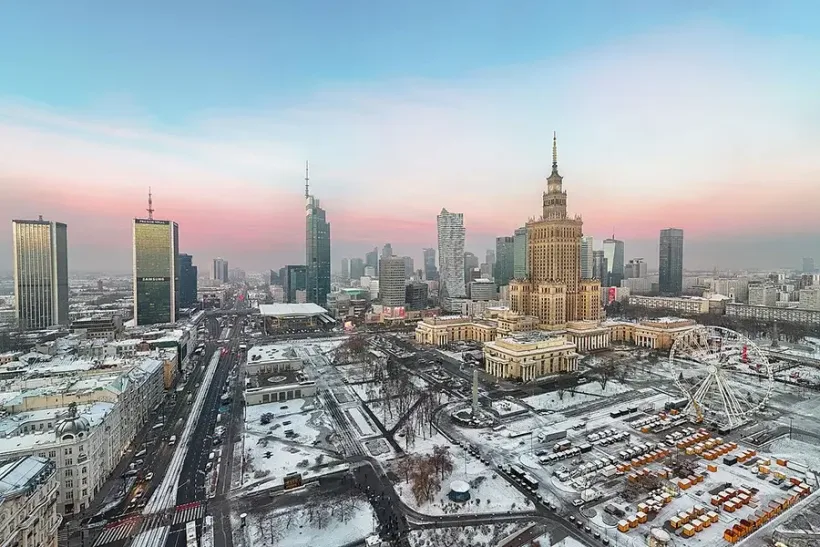
Quintin Soloviev, Wikimedia Commons, CC BY 4.0.
European real estate investment is growing, but capital is becoming much less evenly distributed across the continent. Investment volume is expected to reach €156 billion in the first nine months of 2026, only 4% higher than a year earlier. The regional split is much sharper: Central and Eastern Europe is up 34%, the Nordics 25% and Southern Europe 20%, while the rest of Western Europe is down 5%. The UK, Germany and France are down 8% as a group. Europe’s largest markets remain deeper and more liquid, but geography alone no longer guarantees capital inflows.
Europe is up 4%, but the map is changing faster
Savills expects European real estate investment to reach around €156 billion in January–September 2026, up 4% year on year.
Central and Eastern Europe is forecast to rise 34%, the Nordics 25% and Southern Europe 20%. The rest of Western Europe is down 5%, while the UK, Germany and France are around 8% below the equivalent period last year as a group.
This is not an exodus from Western Europe. Preliminary third-quarter volume across Europe is around €46 billion, 6% below a year earlier. Financing uncertainty and price discipline are slowing decisions across the continent. What is changing is the relative attractiveness of individual markets.
CEE offers income and constrained supply
Central and Eastern Europe has not become risk-free. It has become more competitive on the income investors receive for taking that risk.
CEE office investment reached €1.5 billion in the first half of 2026, 6% above the five-year average for comparable periods. European office investment overall remains about 30% below its equivalent five-year benchmark.
Average office vacancy across the tracked CEE markets fell to 8.1%, compared with 9.4% across Europe. Prime rents increased 9.6% in Warsaw, 7.1% in Budapest and 3.3% in Prague over 12 months.
Prime office yields also remain substantially higher than in major Western European markets: around 6.0% in Warsaw, 5.25% in Prague, 6.75% in Budapest and 7.2% in Bucharest, compared with the low-to-mid 4% range in core Western markets.
With financing still expensive, income matters more than the prospect of simple yield compression.
Poland is receiving capital from within the region
The source of investment is changing as well.
Poland is increasingly receiving capital from neighbouring countries, particularly Czech funds. Over the last 12–18 months, Czech investors have also expanded their activity into the UK and Germany.
This makes CEE less dependent on whether large US or UK institutions increase or reduce their regional allocations. Domestic funds, insurers and private capital are creating a deeper intra-regional market.
Poland also benefits from industrial, logistics and defence-related demand, while limited new office development supports prime Warsaw rents.
Czech real estate has a domestic buyer base
The Czech market provides an even clearer example.
Commercial real estate investment reached approximately €1.4 billion in the first half of 2026. Around €1 billion was completed in the second quarter alone.
Domestic funds and companies accounted for 74% of quarterly volume, while living assets became the largest sector, narrowly ahead of offices.
A strong local investor base improves liquidity but also changes pricing. CEE no longer automatically offers foreign buyers a large discount when domestic capital is willing to compete for the same prime assets.
Spain is growing much faster than the EU average
Southern Europe offers a different investment story.
Spain combines economic growth, tourism, housing shortages and deep rental demand. It is no longer primarily a post-crisis value market.
Eurostat’s latest figures show Spanish house prices rising 12.1% year on year in the second quarter of 2026, compared with 4.7% across the EU.
That growth supports existing owners but raises the entry price for new capital. Hotel, logistics, student housing and rental-residential assets can still be supported by underlying demand, but a strong national story no longer makes every acquisition attractive.
Italy is being supported by large deals
Italy’s recovery is more dependent on major transactions.
Capital is active in retail, hospitality and logistics, including parts of the shopping-centre market that institutional investors had treated cautiously for several years.
The pattern reflects a broader shift. Investors are less committed to fashionable sectors and more willing to buy an asset class when price and cash flow make sense.
The Nordics are growing without a peripheral discount
A 25% rise in Nordic investment undermines any simple West-to-East interpretation.
Sweden had a strong first half supported by large transactions, while domestic and Norwegian buyers remain active.
These are mature and transparent markets, not low-cost peripheral alternatives.
The common factor is therefore not geography. Capital is moving toward markets where pricing, financing and operating fundamentals line up.
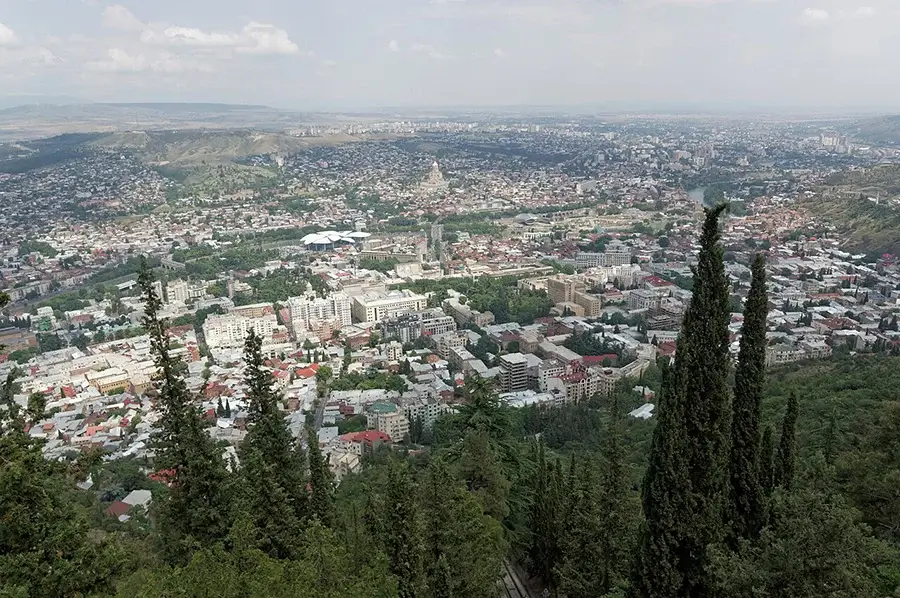
Tbilisi. Georgia sits outside the Savills CEE sample but competes for part of the same international property capital as an earlier-stage market. Photo: Vyacheslav Argenberg, Wikimedia Commons, CC BY 4.0.

Georgia sits outside the European comparison
Georgia is not an EU member and is not included in Savills’ CEE figures.
It nevertheless competes for international capital in housing, hospitality and resort real estate. Its investment proposition is based on a lower market base and earlier-stage development rather than the institutional depth of Poland or Czechia.
Tbilisi recorded 3,388 apartment transactions in August 2026, up 18.9% year on year, while market value increased 35.2% to $297 million. Foreign buyers accounted for around 14% of purchases.
Batumi recorded 1,235 transactions, down 4.3%, while value increased 2.9% to $81 million. Foreign buyers accounted for 52% of sales.
The two cities therefore offer different investment models: Tbilisi is driven more by year-round urban demand, while Batumi is much more exposed to tourism and international buyers.
Georgia competes on demand, not only entry price
Tourism provides a durable demand base for part of Georgia’s property market.
Georgia generated $4.69 billion in international travel revenue in 2025 and recorded 5.52 million international tourist visits. In the first half of 2026, visits from the EU and UK rose 23.4% to a record 249,201. Revenue from those markets increased 21.2% to $335.7 million.
The composition of Batumi supply is equally important.
Galt & Taggart estimated around 18,000–20,000 short-term rental apartments in the city at the end of 2024, with the total potentially reaching 35,000–40,000 by 2029. Internationally branded hotel stock is much smaller, with around 3,764 rooms expected in 2026.
The issue is not a general accommodation shortage. The internationally branded, professionally managed hospitality segment is simply much smaller than the mass apartment market.
Wyndham illustrates the more institutional format
Wyndham Grand Batumi Gonio belongs to this narrower segment.
The project catalogue lists 494 units, including hotel rooms, penthouses, townhouses and villas, under the Wyndham Grand brand. Aimbridge Hospitality is named as the management company.
For an owner, the structure differs from a standalone short-term rental apartment. Pricing, reservations, guest services and daily operations sit inside a central hotel system.
That does not remove project risk. Delivery, operator performance, contract terms and entry price remain critical. But the relative scarcity of professionally managed branded supply gives the segment a different investment case from the mass apartment market.
Georgia’s attraction therefore lies in market stage rather than price alone.
Western Europe is no longer the automatic default
The 2026 shift can easily be overstated as capital fleeing Germany and France.
The data do not support that conclusion.
Western European markets remain the deepest, most liquid and most familiar institutional markets on the continent. Investors simply have to pay more for that predictability and usually accept lower current yields.
CEE offers stronger income but carries more regional risk. Spain and Italy offer faster growth in selected sectors but have already repriced materially. Georgia is earlier in the cycle and requires much more project-specific due diligence.
Europe’s investment map is changing not because mature Western markets have stopped being attractive, but because investors are comparing asset prices more strictly with current income and demand quality. That gives CEE, Southern Europe and selected markets outside the EU more room to compete. Georgia can benefit, particularly in Tbilisi and professionally managed hospitality, as long as demand keeps pace with new supply.
FAQ: European Real Estate Investment in 2026
How much is being invested in European real estate?
Savills expects around €156 billion of investment in the first nine months of 2026, up 4% year on year.
Which European regions are growing fastest?
CEE is up around 34%, the Nordics 25% and Southern Europe 20%. The rest of Western Europe is down about 5%, while the UK, Germany and France are down around 8% as a group.
Is capital abandoning Western Europe?
No. Western markets remain deeper and more liquid. Their relative advantage is weakening because investors are comparing income and growth prospects more aggressively.
Why is CEE attracting investors?
The region combines higher yields, rental growth in selected cities, constrained prime supply and a growing base of domestic institutional capital.
What is happening in Poland?
Warsaw benefits from limited new office supply and rising prime rents, while Czech and other regional investors are becoming more active buyers.
What is happening in Czech real estate?
Commercial property investment reached approximately €1.4 billion in the first half of 2026, with domestic investors accounting for 74% of second-quarter volume.
Why is Spain attractive?
Spain combines economic growth, tourism, housing shortages and deep hospitality, rental and logistics markets. House prices were 12.1% higher year on year in Q2 2026.
Is Georgia included in Savills’ CEE data?
No. Georgia is discussed separately as an adjacent international investment market.
What is happening in Tbilisi property?
August transactions rose 18.9% to 3,388, while market value increased 35.2% to $297 million.
Why does Batumi require more caution?
Foreign buyers account for 52% of transactions and the short-term rental apartment stock is expanding rapidly, increasing competition in the mass investment segment.
Why can branded hospitality in Georgia be attractive?
Internationally branded hotel supply remains much smaller than the private apartment market. Professionally managed assets offer a different way to access tourism demand, although project and operator risks still need to be assessed individually.