





 Sweden Property Investment Climbs 40% in Nine Months
 Hotels Use AI for Pricing but Keep Humans in Charge
 Georgia's Hotel Market: Batumi Room Rates Surge as Tbilisi Occupancy Climbs
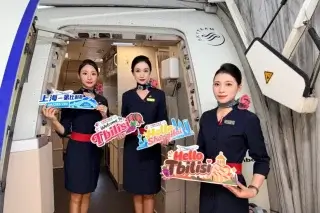 China Eastern Airlines to Boost Shanghai – Tbilisi Flight Frequency to Five Times Weekly from 2027
 Belgian Industrial Property Draws €537m of Capital
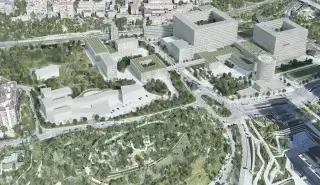 Madrid to Build €1 Billion City of Health Complex
Seoul Hotel Demand May Outpace Room Supply Until 2032
Seoul is entering a hotel investment cycle in which demand is expected to expand much faster than available accommodation. Roughly 3,900 hotel rooms are scheduled to be added between 2026 and 2032, representing an increase of about 7% in supply. Under a conservative scenario, CBRE Korea estimates that inbound demand could reach an index level of 132 by 2032, compared with a hotel room supply index of 107. Both measures are set at 100 in 2025.
The forecast appears in a November 9 CBRE report on hotel valuations, rebranding and the balance between development and visitor demand in the South Korean capital.
A conservative demand scenario still leaves a gap
The study assumes 4% annual growth in international visits, about half the 7.9% average recorded in 2010–2019. Inbound travel to Seoul actually increased 21.5% year on year during the first nine months of 2026, CBRE says. The much stronger recent performance is one reason the research sees a persistent supply-demand imbalance.
The city's planning changes may eventually encourage more development. Seoul has allowed eligible hotels in specialised tourism accommodation districts to increase their floor area ratios to as much as 1.3 times their earlier levels. But projects under those provisions are unlikely to deliver rooms before 2029, given planning, financing and construction timelines.
The limited pipeline is also unevenly distributed. Luxury and Upper Upscale hotels account for 44% of approximately 3,900 planned rooms. Gangnam, where room inventory has fallen by 8% since 2019, is expected to receive 34% of new supply. The Central Zone would receive 32%, below its current 39% share of existing rooms, despite its importance in spending by overseas travelers.
Occupancy has little room to rise
Seoul hotel occupancy reached 76% in 2025, its highest reading since 2015. CBRE compares this level with New York's 84% and estimates that closing the gap would increase occupied-room volume by only around 8%. Rising demand would therefore be expected to show up increasingly in room rates.
Upper Midscale hotels recorded RevPAR in 2025 at 2.3 times their 2019 level. RevPAR measures revenue per available room and captures the effect of both occupancy and average daily rate. For investors, that improvement must be considered together with payroll, energy, distribution costs and the expense of maintaining or upgrading the property.
Hotel supply is often discussed as a single citywide number, but the economics of a limited-service property in one district can be very different from those of a luxury hotel in another. CBRE argues that location, class and operating contracts are becoming more important to asset valuation as occupancy approaches a ceiling.
Lower cap rates meet higher financing costs
Hotel capitalisation rates in Seoul declined from approximately 6.9% in 2024 to 5.1% in 2026, according to CBRE. Over a recent one-year period, the three-year bank bond yield rose from 2.68% to 4.40%. The two metrics serve different purposes: a cap rate relates property operating income to its valuation, while a bond yield reflects market funding conditions.
Investors buying at compressed yields have less room for adverse changes in operating costs or financing assumptions. A master lease may provide more predictable cash receipts for a leveraged owner, while hotel management agreements offer different exposure to operating performance. Each structure affects which party bears risk and receives the upside.
CBRE models an Upscale hotel with a 35% gross operating profit margin and room revenue equal to about 40% of total turnover. Under its example, management contract charges can amount to 5–7% of total revenue, compared with 3–5% for franchise brand charges. These are illustrative operating assumptions, rather than quoted terms for an individual Seoul hotel.
Rebranding can change the value proposition
A recent sale illustrates the research's focus on asset enhancement. The voco Seoul Myeongdong property was purchased for KRW228.2 billion, refurbished and relaunched under IHG's voco brand, and then sold in June 2026 for KRW368.6 billion. The reported price per room increased by about 60%, from approximately KRW400 million to KRW640 million.
The increase also reflected broader market changes, including cap rate compression, during the holding period. Owners evaluating similar projects must therefore consider renovation costs, changes to demand, the purchase price and the market's valuation cycle.
CBRE divides the coming years into three phases. Through 2027, constrained supply could make pricing the main driver of performance. During 2028–2029, lower interest rates may support valuations. From 2030 onward, additional rooms could increase the difference between well-positioned and less competitive assets.
The outlook also depends on visitor trends and policy. The current visa-free arrangement for organised tour groups from mainland China is scheduled to expire at the end of December 2026, creating another variable for travel demand.
Seoul's hotel investment market is becoming more dependent on active decisions about location, brand, financing and asset quality. The citywide shortage may support trading conditions, but investment returns will be determined by individual properties and the contracts under which they operate.
EN · FAQ
How many new Seoul hotel rooms are expected through 2032? CBRE forecasts approximately 3,900 between 2026 and 2032.
What does CBRE's demand index of 132 mean? It is the modelled 2032 demand level with 2025 set to 100, compared with a room supply index of 107.
What was Seoul's hotel occupancy in 2025? CBRE reports 76%.
Does hotel rebranding guarantee returns? Property-level returns depend on acquisition price, spending on upgrades, financing and operational agreements.