







 Russia May End Its IT Mortgage Program Early
 Batumi Real Estate Market: Sales Rise as Growth Dynamics Shift — Galt & Taggart
 Wizz Air Launches Domestic Flights in Spain
 Prime London Rents Rise as Landlords Hold Back
 AI in Hospitality: Practical Applications and Future Prospects
 Gemofest: “Your Personal Guide to Discovering Georgian People and Georgian Cuisine” — Wanderlust
Dublin Warehouse Leasing Jumps 65% in Q3
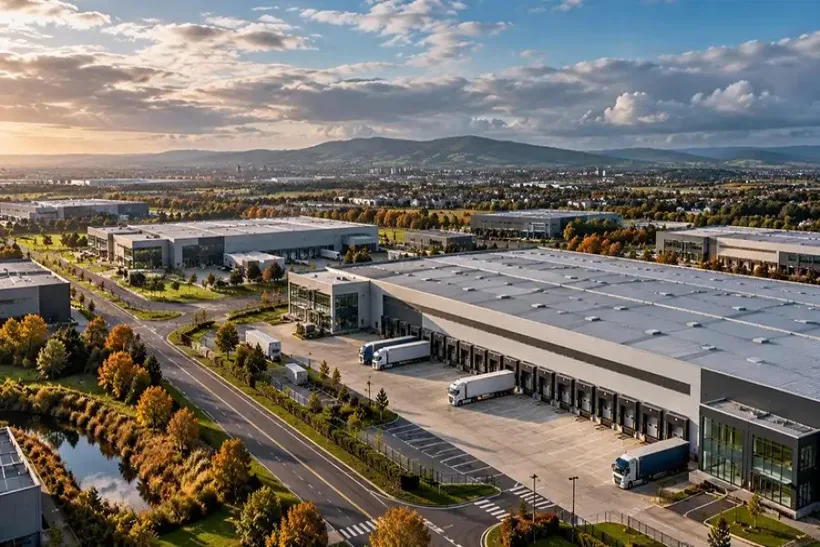
Industrial and logistics occupiers leased 824,400 sq ft of space across Dublin during the third quarter of 2026, a 65% increase from a year earlier. Savills Ireland reported 17 transactions in its 19 October market update, making it the strongest quarter since Q4 2023. Take-up reached 1.9 million sq ft over January–September. The measure describes space leased by occupiers, not the amount investors spent buying property or the quantity of new buildings completed.
Larger deals drive the strongest quarter since 2023
Four leases exceeded 100,000 sq ft, lifting the average transaction size to 48,500 sq ft — the highest figure in almost three years. Such a concentration makes the headline take-up sensitive to a relatively small number of major occupier decisions. The increase is therefore better understood as renewed demand for large, modern facilities than as proof that every Dublin industrial submarket is expanding at the same pace.
Third-party logistics providers accounted for 48% of the area taken, industrial occupiers for 23% and first-party logistics operations for 21%. Almost half the space leased was in buildings completed after 2020. These indicators highlight tenants' preference for more recent stock, although the report does not by itself show that new construction in every location can be leased on equally favourable terms.
South-West Dublin captures 84% of space leased
South-West Dublin accounted for 84% of quarterly take-up, compared with a five-year average share of 52%. All five of the quarter's largest transactions were in this area. Two of them involved Mountpark Grange Castle West, where more than 450,000 sq ft of speculative development delivered in the previous year has since been leased.
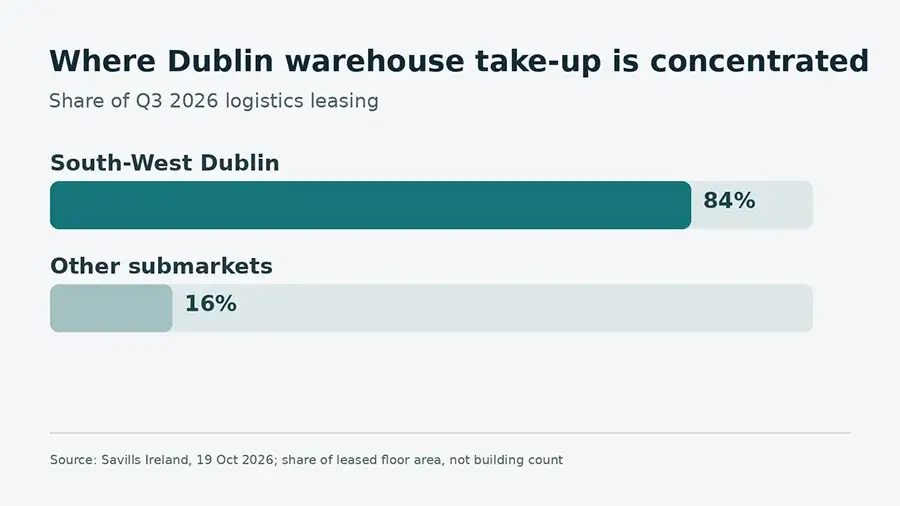
Share of Dublin industrial and logistics take-up in Q3 2026: South-West Dublin 84%; all other submarkets 16%. Original editorial chart based on Savills Ireland, 19 October 2026. ALT EN: bar chart showing where Dublin's warehouse leasing concentrated.
Vacancy in the south-west declined from 3.1% in Q2 to 1.5% in Q3, while Dublin's overall rate eased from 2.8% to 2.6%. These are shares of available stock, not rental-growth rates. For occupiers requiring one large warehouse, very limited available supply in a specific location can matter more than the citywide vacancy average.
Prime logistics rents rise for a sixth quarter
Prime quoted rents increased by €0.25 per sq ft during Q3 to €14.75 per sq ft per year, marking a sixth consecutive quarterly rise. The annual increase was €1 per sq ft. Secondary rents reached €11.75. These are market benchmarks rather than universal contracted rates: incentives, building quality and lease terms can change a tenant's actual cost.
International Investment's earlier overview of Dublin commercial property examined why constrained supply has supported industrial rents, while the Savills European logistics outlook described growing tenant demand for modern, energy-efficient accommodation. The latest city-level figures provide a more precise test of those broader themes.
The development pipeline may ease pressure in 2027
About 405,100 sq ft of industrial and logistics accommodation was completed in Q3, with another 199,800 sq ft expected before the end of 2026. Savills estimates that annual deliveries could exceed one million sq ft, still below the five-year average of 1.4 million. Approximately 1.4 million sq ft is scheduled for completion in 2027, but construction schedules are forecasts rather than confirmed additions to occupied supply.
Investors should read leased area, vacancy and development pipelines as distinct measures. Strengthening occupier demand can support rental growth where available buildings are scarce, but it does not guarantee capital appreciation or the performance of an individual asset. Financing costs, covenant strength, lease duration, power availability and refurbishment needs remain central to valuation.
Frequently Asked Questions (FAQ)
How much Dublin logistics space was leased in Q3 2026? Savills recorded 824,400 sq ft across 17 transactions, up 65% year on year.
Which area led Dublin industrial take-up? South-West Dublin accounted for 84% of the floor area leased in the quarter.
What was the vacancy rate? Vacancy stood at 2.6% across Dublin and 1.5% in the south-west.
How much do prime logistics properties rent for? Savills quotes €14.75 per sq ft annually as a prime market benchmark, not a universal contractual rate.